All Categories
Featured

Tips for Managing Attorney Costs in 2026
Table of Contents
Personal bankruptcy legally allows people or businesses who are unable to repay their financial obligations to look for relief through court-supervised reorganization or liquidation (sales) of assets. It offers a fresh financial start for debtors while making sure reasonable treatment of creditors, however experts state it ought to be a last hope to settle your financial issues.
While personal bankruptcy frequently brings a stigma, it's crucial to set aside those concerns and focus on finding an option that can offer relief. "The greatest mistaken belief, by far, is that personal bankruptcy is a BAD thing," said Adrienne Hines, author of "Bankruptcy Magic: The Life-Changing Power of Debt Relief with Dignity" and a personal bankruptcy and employees compensation lawyer with Wisehart & Wright, Co., LLC, in Sandusky, Ohio.
2026 Financial Relief and BankruptcyBeing smart about your options and exploring your options are more vital than being embarrassed or ashamed.": A private or organization that owes money, items, or services to another party. A bank, individual, service or other organization that lends money, extends credit, or provides services with the expectation of being paid back, usually with interest.
: A court order that releases a debtor in personal bankruptcy from liability for specific financial obligations and forbids lenders from continuing to try to gather them. The procedure in which a few of a debtor's properties are sold to pay off creditors. Financial obligation that is backed with collateral such as a home or vehicle, which a creditor can take if you default on a loan.
Insolvency provides lenders an opportunity to be a minimum of partially repaid when assets belonging to an individual or service are liquidated, meaning the properties are transformed into money which is then turned over to the debtholders. All insolvency cases are submitted in federal court. Judges take a look at the insolvency filing to identify a debtor's eligibility and after that decide whether to discharge that debt.
Mastering the Current Bankruptcy Landscape
Most cases are handled in between the judge and trustee and don't need the debtor to appear in the court proceedings. A decision can be made to release, meaning the debtor is no longer legally accountable for paying those debts. Or the judge might dismiss the filing if he or she thinks the individual or company has the ways to pay their financial obligations.
Declare bankruptcy can be a saving grace for individuals drowning in debt. The numbers support that contention. The American Personal bankruptcy Institute states that 95.3% of individuals in Chapter 7 bankruptcy achieve success when they are represented by a lawyer, and United States. Bankruptcy Court data reveal an even greater portion in Chapter 7 cases that aren't dismissed or transformed into another type of personal bankruptcy As you'll see below, you might have to qualify for Chapter 7 insolvency based on your income.
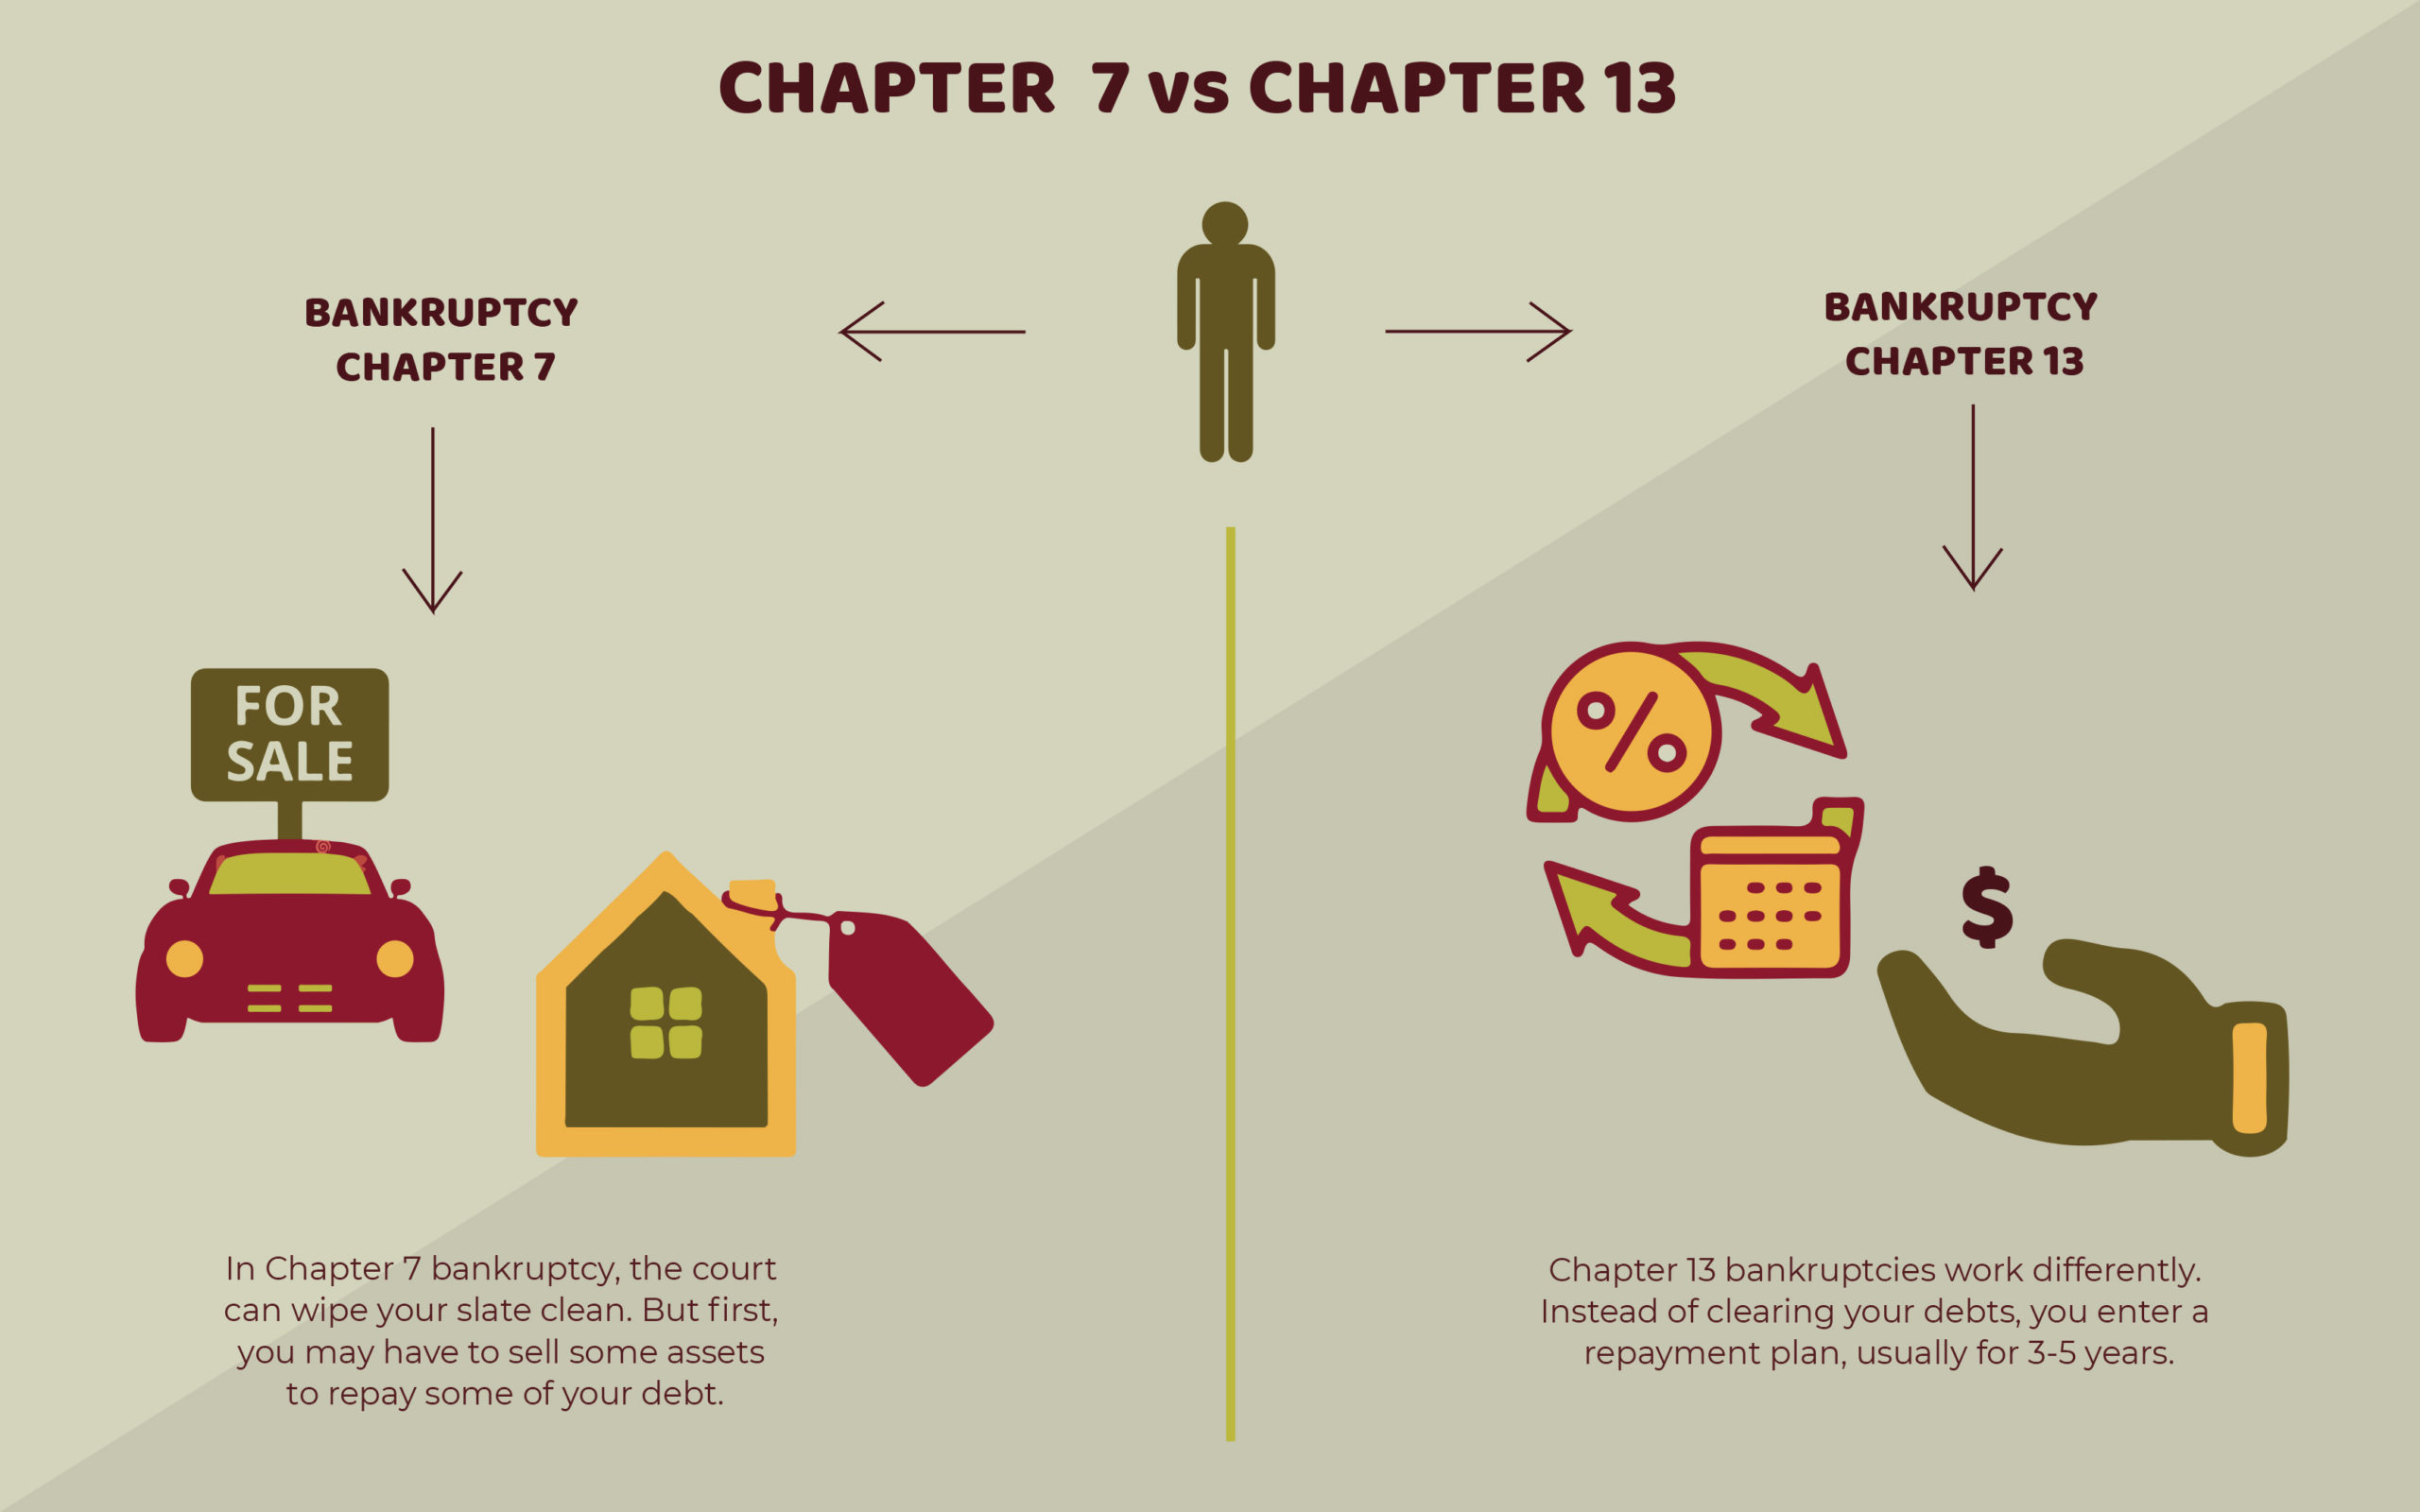
Comprehending these choices can help people and companies pick the finest course to fix their debts and regain financial stability. Chapter 7 and Chapter 13 are by far the most typical types of insolvency, accounting for over 98% of insolvency filings based on early 2026 information.
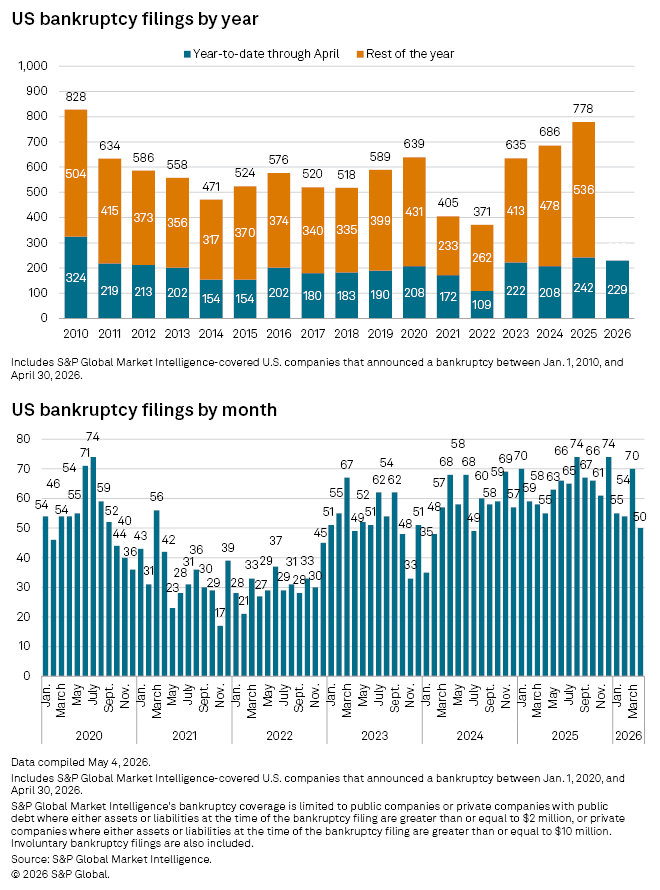
Historically, it's been the most widely used kind of personal bankruptcy since it's comparatively inexpensive and supplies the quickest debt relief. That pattern is continuing, as Chapter 7 filings increased by 17% in the very first quarter of 2026 over the very first quarter of 2025, according to data from Epiq AACER released by the American Bankruptcy Institute.
Strategies for Reducing Attorney Fees in 2026
You also could be allowed to keep crucial assets thought about "exempt" property, though non-exempt residential or commercial property will be offered to repay part of your financial obligation. Feel in one's bones that residential or commercial property exemptions differ state-to-state. By the end of an effective Chapter 7 filing, the bulk (or all) of your financial obligations will be discharged, meaning you won't need to repay them.
Chapter 7 bankruptcy remains on your credit report for 10 years and significantly reduces your credit score, however your rating could enhance with time as you restore your finances. While some individuals may not qualify due to high income, others merely can't afford Chapter 7 insolvency due to the charges and expenses.
A Chapter 13 insolvency involves reorganizing your finances so you can repay some debts in order to have actually the rest forgiven. This is an option for people who do not wish to quit their property or do not get approved for Chapter 7 since their income is too high. People can just declare personal bankruptcy under Chapter 13 if they have less than $526,700 in unsecured debt in cases filed in between April 1, 2025, and March 31, 2028.

Latest Posts
Steps for Filing the Bankruptcy Claim in 2026
Serious Legal Impacts of 2026 Bankruptcy
Reviewing Chapter 7 and 13 Laws for 2026