All Categories
Featured
Table of Contents
instantly upon filing, through the automatic stay. You're behind on your mortgage and desire to keep your homeYour income is above the Colorado typical and you do not pass the Chapter 7 indicates testYou have non-exempt equity you want to secure by paying its worth into a strategy instead of losing the assetYou have financial obligations that make it through Chapter 7 (specific taxes, some domestic support defaults) that you need structured time to payYou have actually filed Chapter 7 too recently to file again (see timing rules below)The methods test under 11 U.S.C.
Stop Wage Garnishment Through 2026 Bankruptcy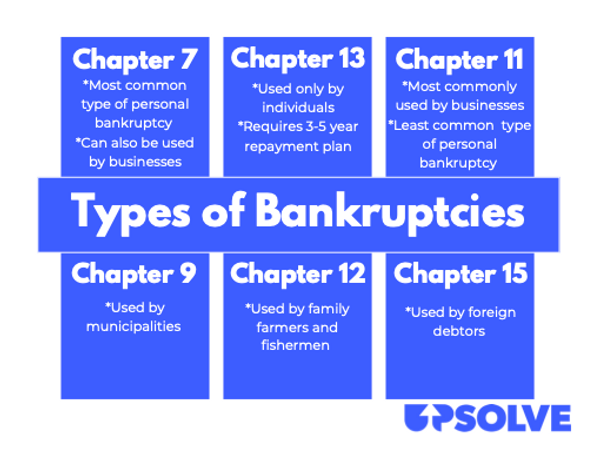
Here's how it operates in plain terms: The U.S. Trustee Program releases mean family income figures by family size, updated every April and November utilizing Census Bureau data. If your typical monthly income over the previous six months, annualized, falls at or below Colorado's typical for your family size, you pass the ways test immediately and might submit Chapter 7.
Guide to 2026 Debt Relief and BankruptcyNumerous above-median filers still qualify for Chapter 7 after these reductions. or you may still have choices depending upon the type of financial obligation you bring (the methods test just uses to filers whose financial obligations are mainly consumer debts). Due to the fact that the mean income figures and internal revenue service expenditure standards change twice a year, the precise numbers that used when a friend or relative submitted might not apply to your case today.
Chapter 13 isn't available to everybody despite income there are statutory debt ceilings under 11 U.S.C. 109(e). As of the most current inflation modification (efficient April 1, 2025, through March 31, 2028), the limitations are different for protected and unsecured financial obligation, in the low seven figures combined. There is active, bipartisan legislation pending in Congress that would raise and streamline these limitations into a single combined threshold worth viewing if you're near the present ceiling, especially if a big home mortgage is what's pressing you over.
Key 2026 Bankruptcy Advice and Strategies
This is generally the deciding aspect for Colorado filers. Colorado's exemption statutes safeguard a set quantity of equity in your house, lorry, tools of trade, pension, and individual property. If your equity in a property goes beyond the exemption, the trustee can sell it and pay you the exempt part however for the large bulk of filers with average equity levels, everything is safeguarded and absolutely nothing is sold.
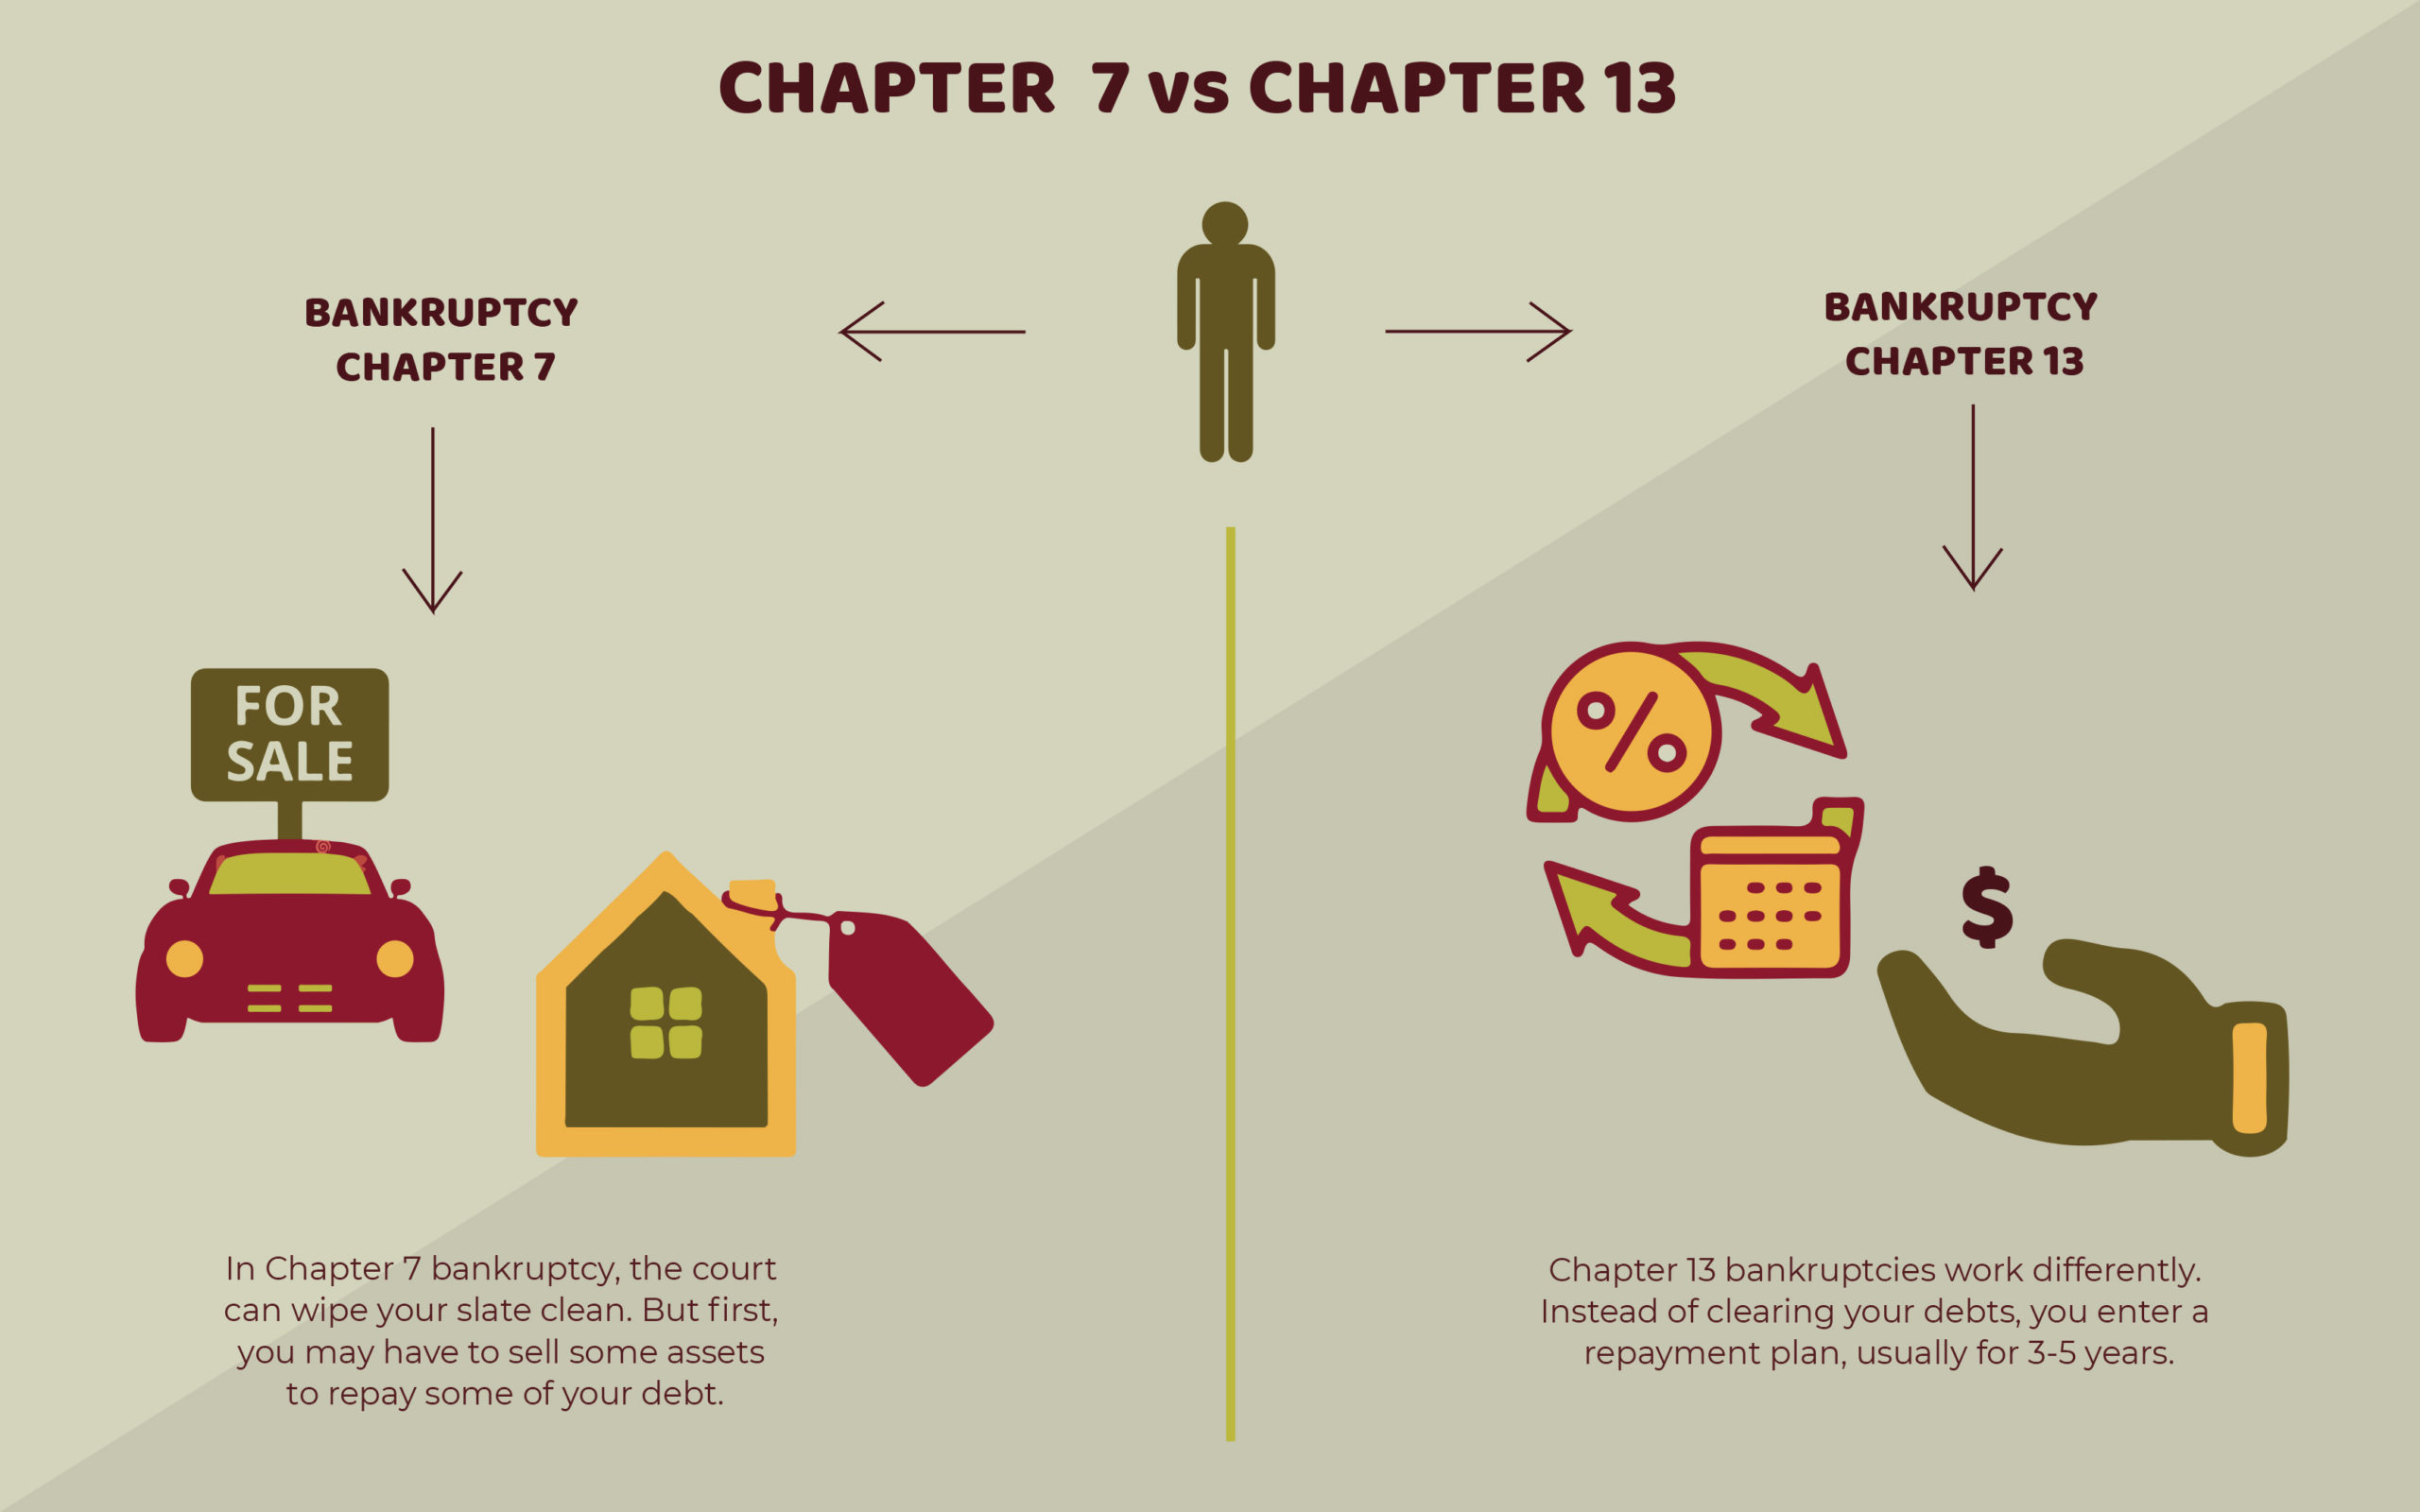
This is often why higher-equity homeowners or service owners pick Chapter 13 even when they may technically pass the Chapter 7 means test. 34 months to discharge35 years to dischargeNoYes, per court-approved planLower, one-timeLower, one-time (plus ongoing trustee cost)Often paid up front or soon after filingFrequently paid through the strategy over timeStays 10 years from filingStays 7 years from filingUnsecured financial obligation with no significant assets at riskSaving a home, treating defaults, above-median earnings Chapter 13 Chapter 7 You normally must wait 8 years for another Chapter 7 discharge, however may receive Chapter 13 earlier (timing guidelines are technical and case-specific) Chapter 13, to treat the default and keep the vehicle Often Chapter 13, though eligibility depends on the "regular income" requirement Chapter 13's co-debtor stay offers security Chapter 7 does notI invested years administering cases as the Trustee -seeing firsthand which choices held up and which ones backfired.
Submitting the incorrect chapter, or filing correctly but with an avoidable mistake, can suggest losing home you might have kept or paying years longer than needed. If you're weighing Chapter 7 vs.

Navigating Between Chapter 7 and 7 for 2026
Yes, in most cases many can convert your case from Chapter 13 to Chapter 7 if your circumstances changeSituations subject to certain restrictions specific constraints approval.
It depends upon your family earnings compared to Colorado's current typical figures for your home size, plus allowed cost reductions if you're above median. These figures change twice a year, so a precise response needs checking the chart in effect on your filing date. Yes. Filing either Chapter 7 or Chapter 13 triggers the automatic stay, which right away stops most wage garnishments, collection calls, and claims.
Chapter 13 offers court-enforced defense that personal debt settlement does not provide, however it's a longer commitment. This article is for basic informational functions only and does not make up legal advice. Personal bankruptcy law is fact-specific, and outcomes depend upon your individual circumstances. Contact our office to discuss your scenario directly.

Latest Posts
Steps for Filing the Bankruptcy Claim in 2026
Serious Legal Impacts of 2026 Bankruptcy
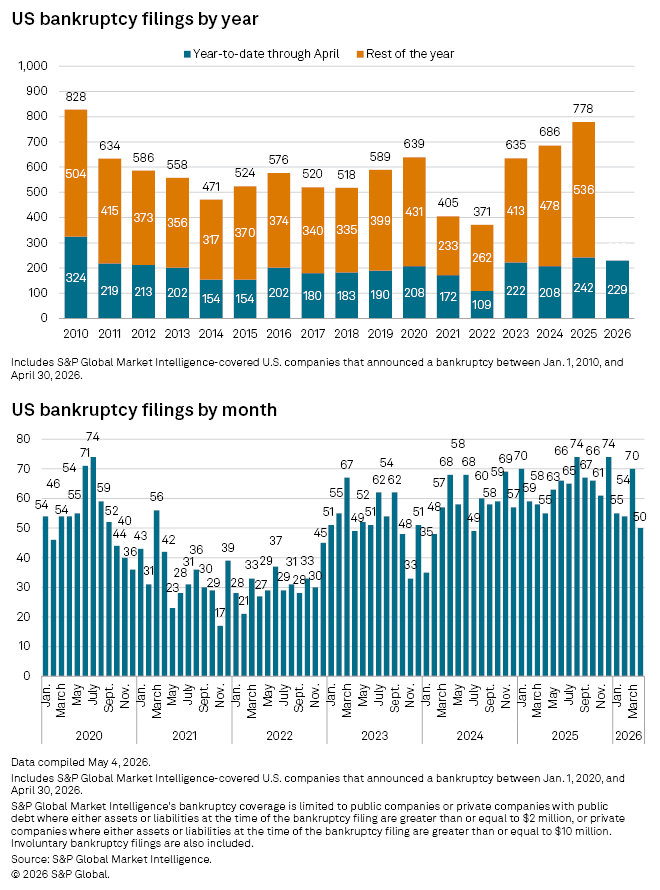
Reviewing Chapter 7 and 13 Laws for 2026