All Categories
Featured

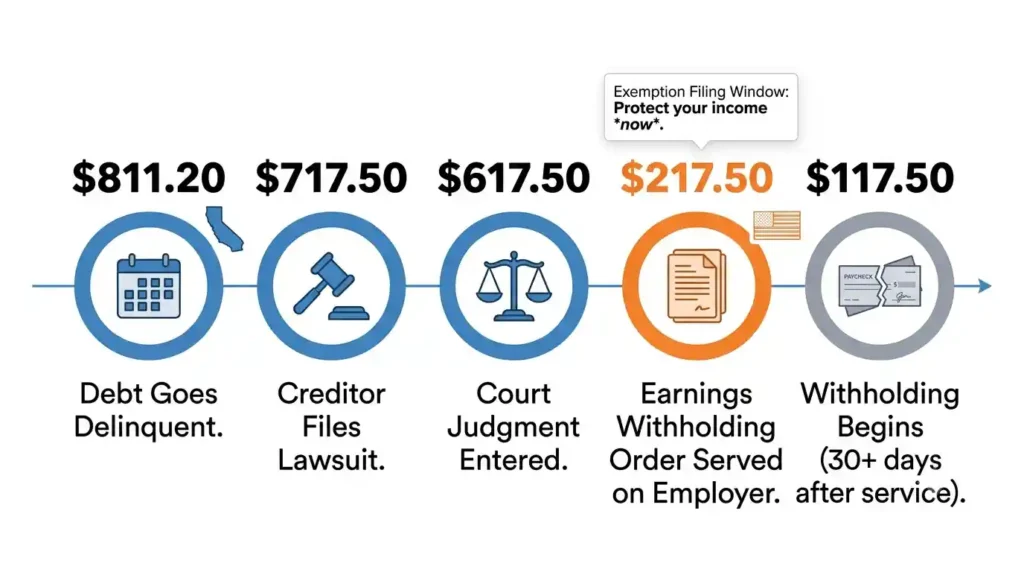
The Guide to 2026 Debt Relief and Bankruptcy
Table of Contents
Say an employee's disposable revenues are $2,000.
No. Under Title III of the Customer Credit Protection Act (CCPA), you can not discharge an employee whose earnings undergo garnishment Nevertheless, the CCPA does not secure workers whose earnings undergo 2 or more garnishments. You should begin garnishing a worker's earnings when you receive a trainee loan garnishment order.
Stop withholding if you get a main notice. You can easily establish a wage garnishment in Patriot's payroll software application. You are responsible for remitting garnishments to the appropriate agencies. You can learn how to establish a wage garnishment here.
Is Chapter 13 the Best Relief in 2026?
The U.S. Department of Education (the Department) today revealed that it will delay the implementation of uncontrolled collections on federal student loans, consisting of Administrative Wage Garnishment (AWG) and the Treasury Offset Program (TOP). The temporary delay will allow the Department to carry out significant student loan repayment reforms under the Operating Families Tax Cuts Act (the Act) to offer debtors more alternatives to repay their loans.
The Act reduces the number of federal student loan repayment strategies, eliminating a complicated maze of alternatives and making it simpler for borrowers to select either a single basic payment strategy or income-driven payment (IDR) strategy that finest fulfills their needs. This consists of a brand-new IDR plan that waives unpaid interest for customers with on-time payments whose payments do not fully cover accumulated interest, and that consists of small matching payments from the Department in specific scenarios to make sure that exceptional principal is minimized every month.
The hold-up in collections will give defaulted debtors extra time to examine these new payment options once they combine their loans or complete a payment or rehab contract. The Act also gives debtors a second opportunity to restore a defaulted loan, enabling them to get their repayments back on track and get the loan out of default.
The delay in collections will give defaulted borrowers extra time to start the rehab procedure, consisting of the ability to restore their loan a 2nd time.
The Trump administration will resume garnishing incomes from trainee loan borrowers in default in early 2026, the U.S. Education Department confirmed to NPR. The move follows a years-long pause in wage garnishment due to the pandemic. "We anticipate the first notices to be sent out to around 1,000 defaulted borrowers the week of January 7," a department representative informed NPR.
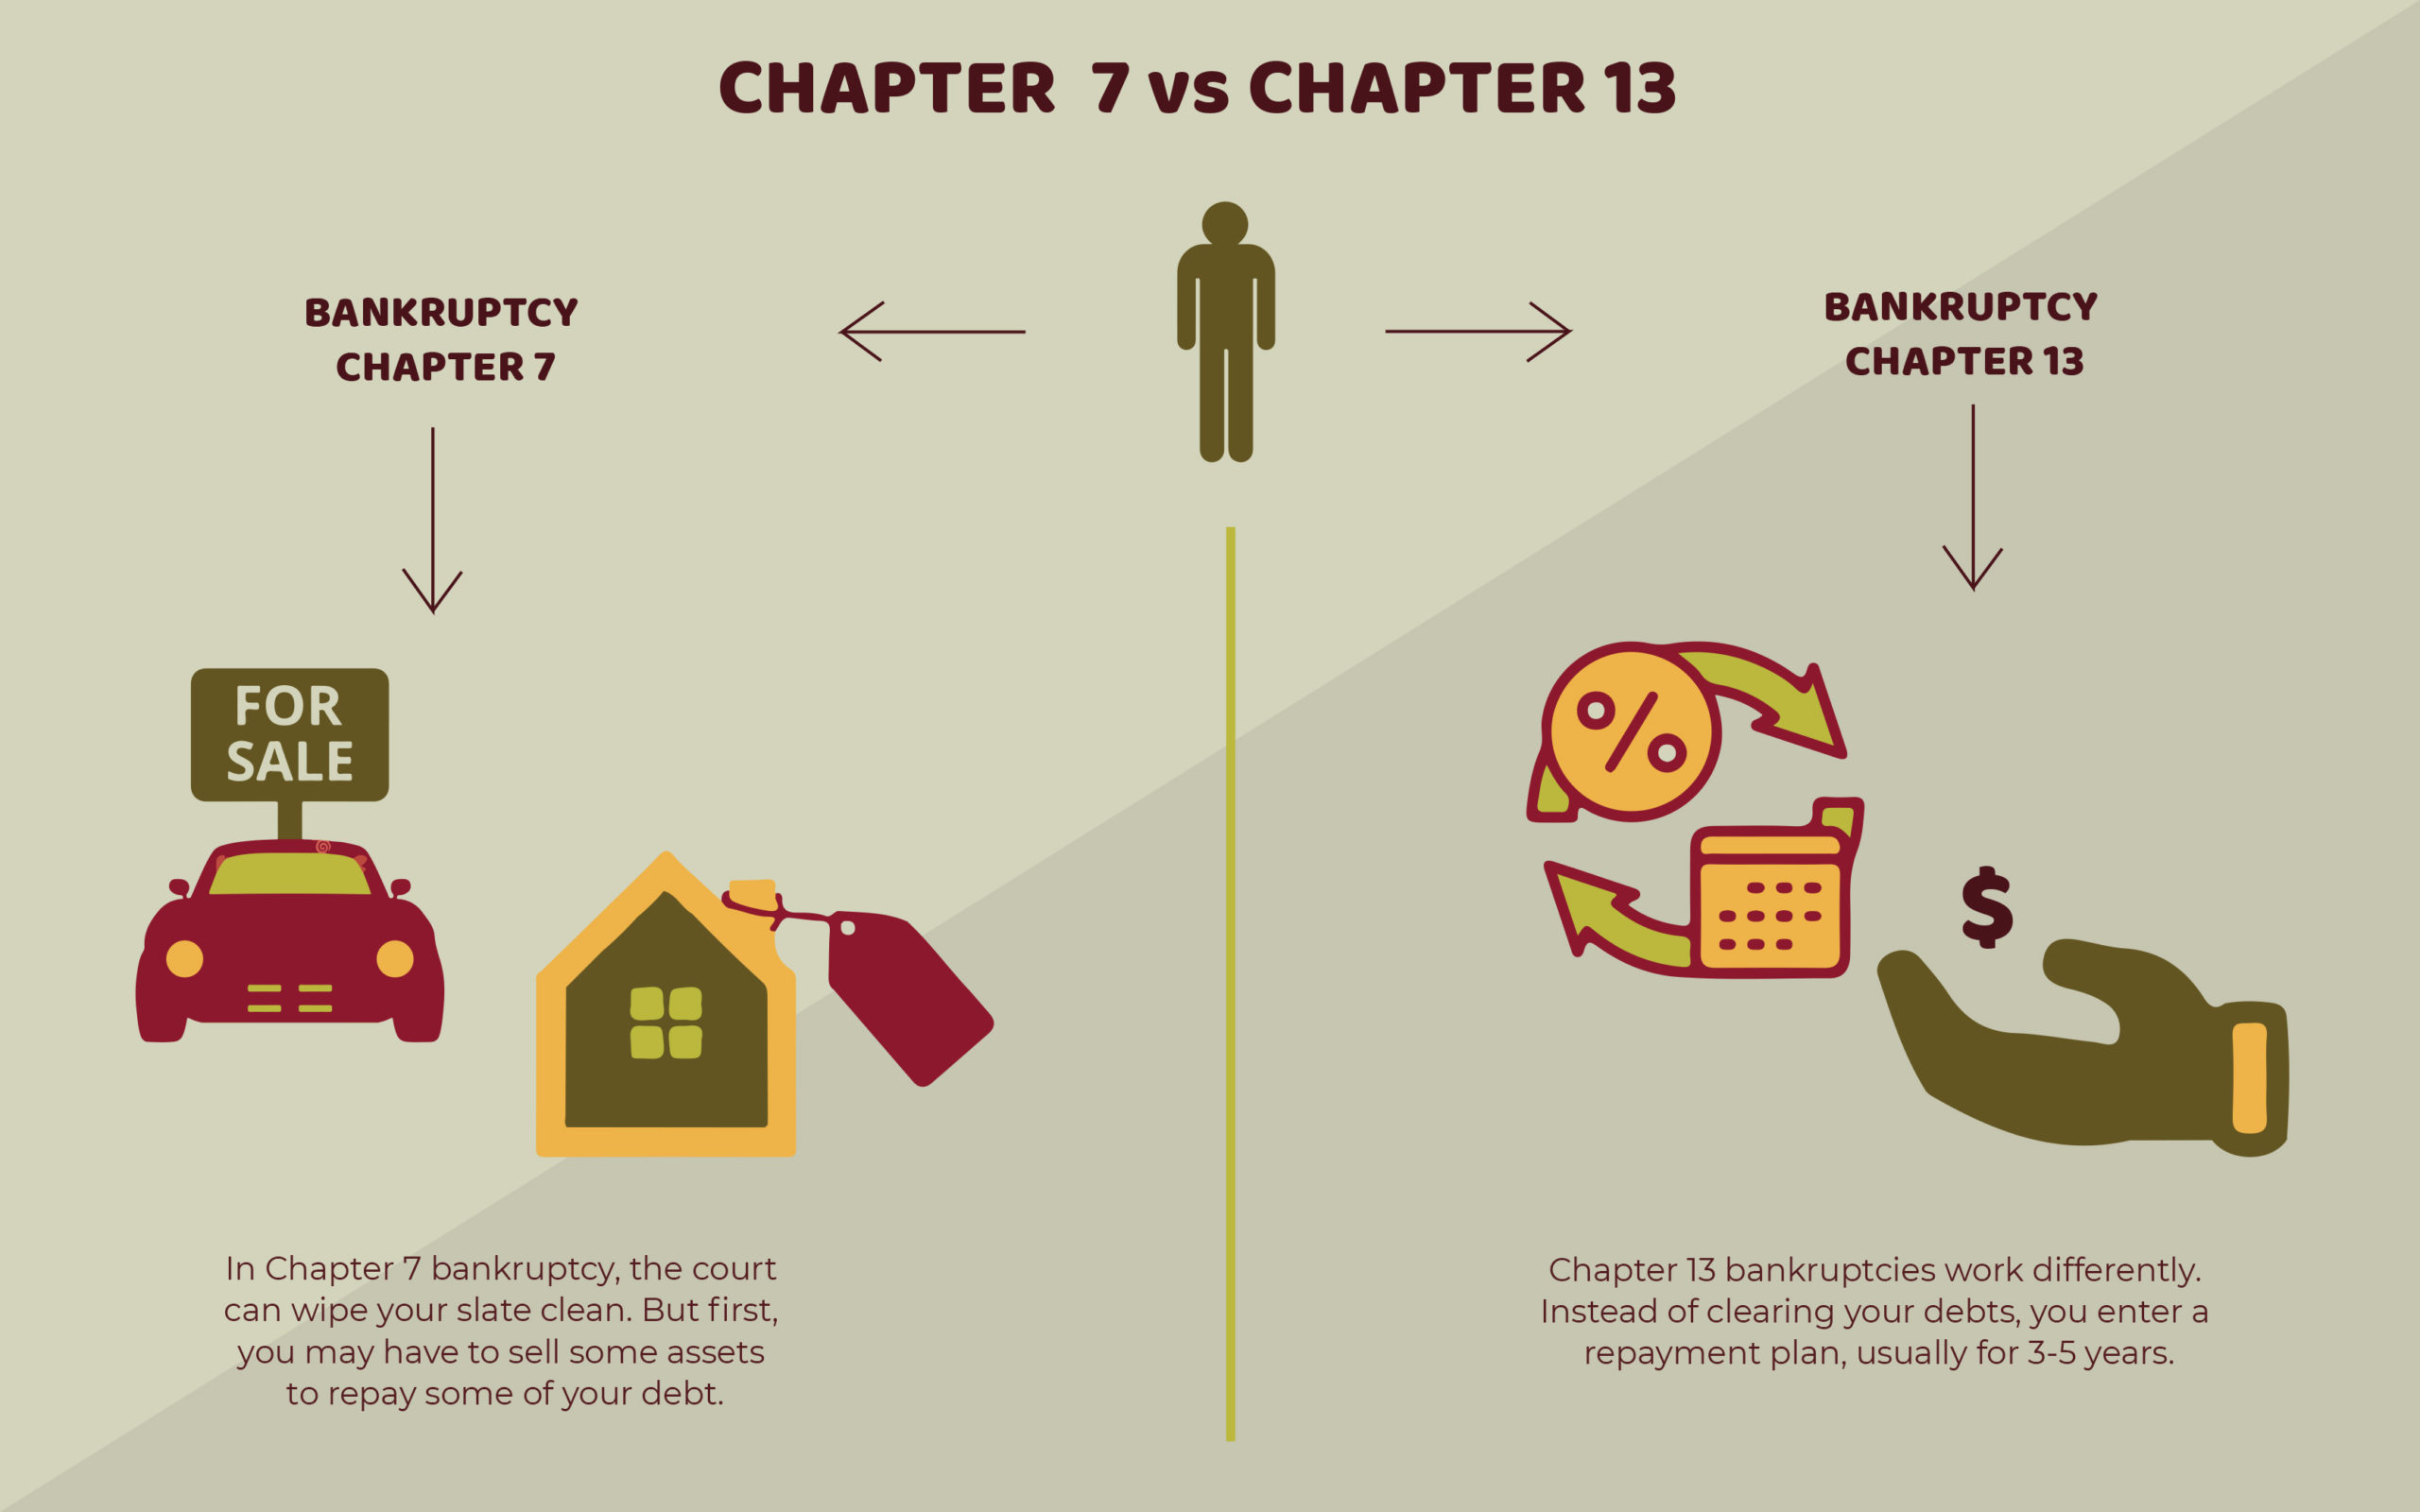
Long-Term Impacts of 2026 BankruptcyComparing Chapter 7 and Chapter 13 Paths
A debtor remains in default when they have actually not made loan payments in more than 270 days. Once that happens, the federal government can attempt to collect on the debt by seizing tax refunds and Social Security advantages, and also by purchasing an employer to keep as much as 15% of a borrower's pay.
Betsy Mayotte, the president and founder of The Institute of Trainee Loan Advisors, says although debtors have actually anticipated this, the timing is regrettable. "It will accompany the increase in healthcare expenses for much of these defaulted customers," she said, referring to the premium increases for Affordable Care Act medical insurance that start in 2026.
Another 3.7 million are more than 270 days late on their payments and 2.7 million are in the early stages of delinquency. "We've got about 12 million customers today who are either overdue on their loans or in default," Preston Cooper, who studies trainee loan policy at AEI, told NPR.
Is Chapter 7 the Best Relief in 2026?
Cory Turner added to this story.
(Article Updated Jan. 6 and 8, 2026) This short article notes federal and state customer law modifications arranged to go into impact or expire throughout the duration from December 1, 2025, through January 1, 2027. Other consumer law modifications will be enacted in 2026 and will go into result in 2026; this short article notes modifications whose efficient dates have already been arranged as of December 31, 2025.

Latest Posts
Steps for Filing the Bankruptcy Claim in 2026
Serious Legal Impacts of 2026 Bankruptcy
Reviewing Chapter 7 and 13 Laws for 2026