All Categories
Featured

Long-Term Consequences of Filing Bankruptcy
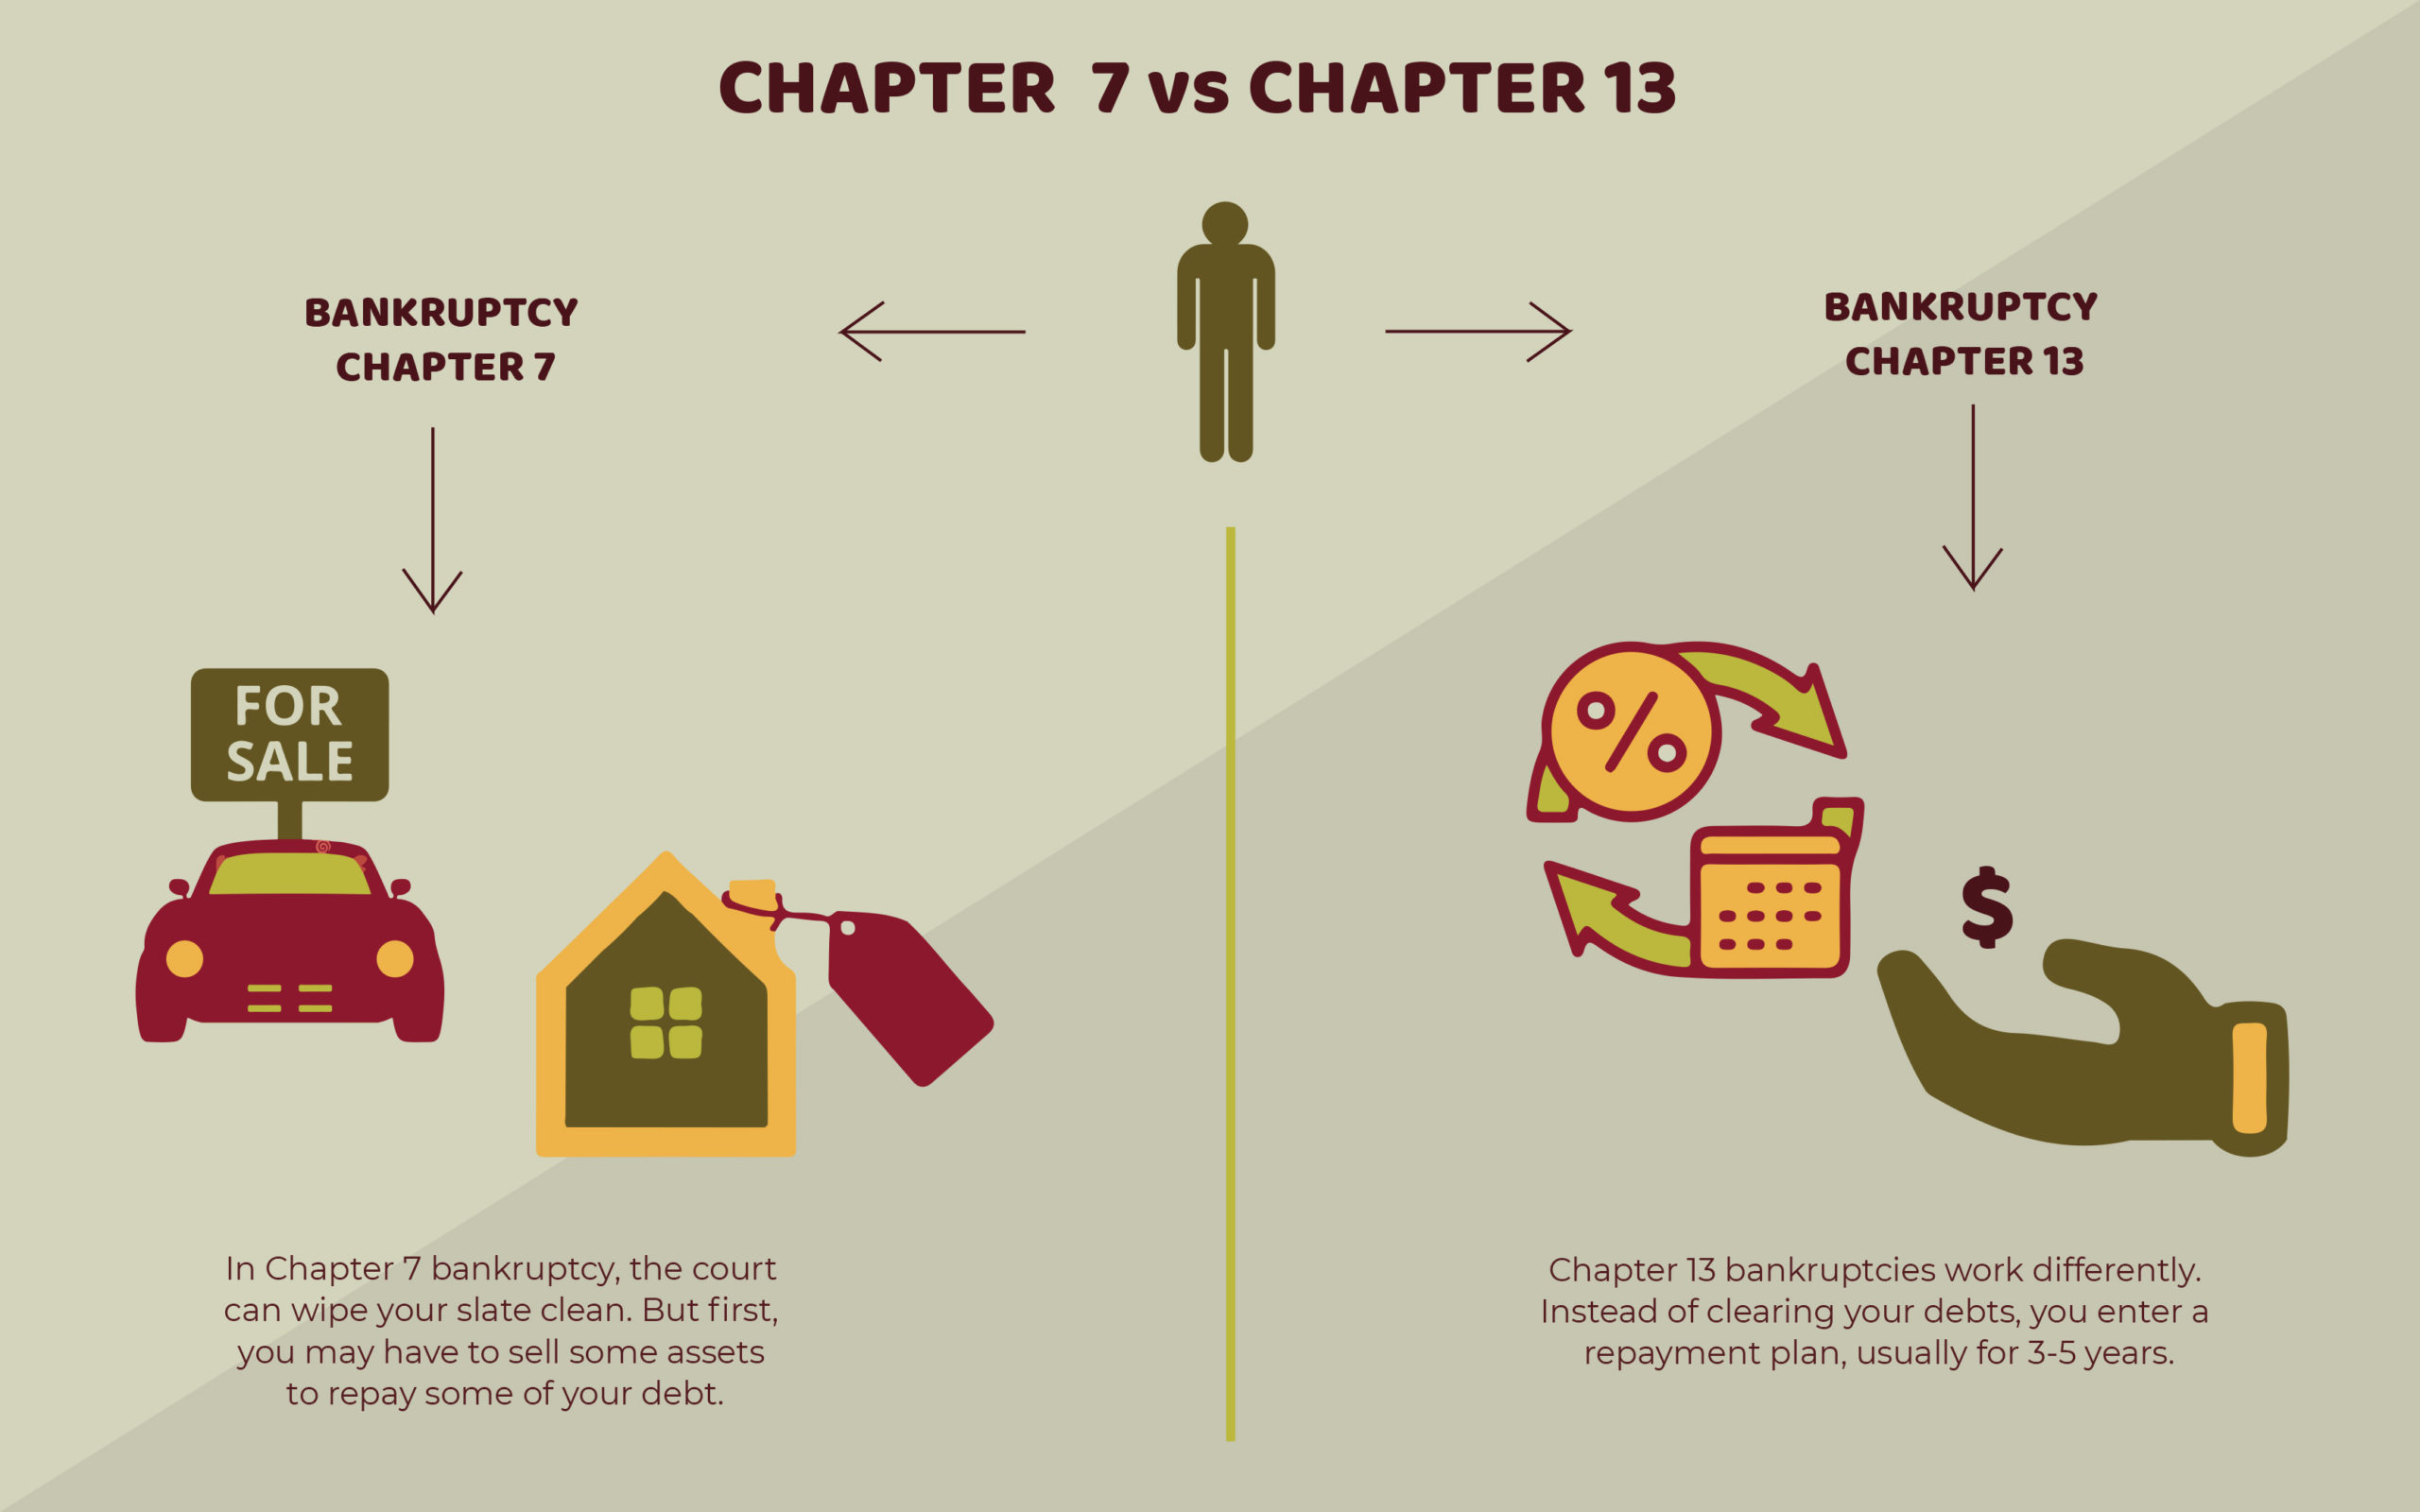
Chapter 7 vs. Chapter 13: Which Bankruptcy Alternative Is Better for Your Financial Scenario? Chapter 7 and Chapter 13 insolvency provide different ways to handle debt, and the much better choice depends upon your earnings, properties, and financial top priorities. Chapter 7 focuses on getting rid of certifying financial obligations in a fairly brief time, while Chapter 13 uses a court-approved payment plan to help you catch up slowly.
Chapter 7, often called liquidation insolvency, is created to remove unsecured debts such as credit cards and medical bills. Under Chapter 13, you make routine payments to a trustee, who then distributes funds to financial institutions. At the end of the plan, any remaining eligible unsecured financial obligation may be discharged.

There is no single response that uses to everyone. The better choice depends on how your earnings, financial obligations, and possessions collaborate. Chapter 7 may make good sense if your earnings is low, your financial obligations are primarily unsecured, and you do not need a long-lasting payment strategy. Chapter 13 might be the much better option if you have a steady income, valuable possessions to safeguard, or past due secured financial obligations that you wish to keep.
Should You Use Chapter 13 in 2026?
Both Chapter 7 and Chapter 13 will impact your credit, but the effect is not long-term. Many individuals begin rebuilding credit sooner than anticipated by paying costs on time and handling brand-new accounts responsibly. Chapter 7 remains on your credit report longer than Chapter 13, while Chapter 13 shows creditors that you followed a court-approved repayment plan.
Choosing in between Chapter 7 and Chapter 13 is a legal decision with long-term effects. Filing without understanding how exemptions, income limitations, and repayment strategies use to your circumstance can lead to preventable issues. When you are facing collection actions, wage garnishment, or mounting costs, getting precise guidance early can help you avoid missteps and move on with self-confidence.
How to File for Bankruptcy Efficiently in 2026At Robert H. Solomon, PC, we deal with people in New York to determine the insolvency solution that fits their objectives and secures what matters most. Contact us to arrange a consultation and take the next step toward financial stability. About the Author Mr. Solomon has actually dealt with thousands of people looking for to acquire a clean slate through bankruptcy.
If debt has actually ended up being uncontrollable, you have actually most likely already searched "Chapter 7 vs Chapter 13 personal bankruptcy" more than as soon as. Both chapters can stop collection calls, wage garnishments, and lawsuits but they operate in fundamentally various methods, and selecting the incorrect one can cost you time, money, or property you were wanting to keep.
Bankruptcy Court Chapter 7 Trustee, I've reviewed thousands of cases from the inside of the system, not simply the outside. Here's a simple, 2026-updated breakdown of how each chapter works, who qualifies, and how to analyze the choice. is a liquidation insolvency. The majority of filers keep whatever through exemptions, and qualified debts are eliminated in about 34 months.
Legal Support for 2026 Bankruptcy Filers
is a reorganization insolvency. You keep your home and pay back some or all of your debts through a court-approved strategy lasting 3 to 5 years. The chapter that's "right" for you depends on your earnings, what you own, what you owe, and what you're trying to secure usually, a house or an automobile you lag on.
A trustee is designated to your case, non-exempt assets (if any) are sold to pay creditors, and many unsecured financial obligations credit cards, medical expenses, personal loans, old utility costs are discharged. A lot of Chapter 7 cases discharge in approximately 90120 days from filing. You aren't required to repay unsecured lenders.
Many filers with a modest home, one or 2 lorries, and normal family products keep whatever. You must certify based on income (more on this listed below). Your income is at or below the Colorado average for your home sizeYou do not have significant non-exempt equity in your home or other propertyYou're existing on your mortgage or auto loan (or prepared to surrender them)You desire the fastest possible path to a dischargeChapter 13 is a payment plan bankruptcy for individuals with regular earnings.

Latest Posts
Steps for Filing the Bankruptcy Claim in 2026
Serious Legal Impacts of 2026 Bankruptcy
Reviewing Chapter 7 and 13 Laws for 2026