All Categories
Featured


End Salary Garnishment with 2026 Bankruptcy Laws
Table of Contents
That's you. If you are overwhelmed with financial obligation, be sure you think about all financial obligation relief options and identify what's best for you.
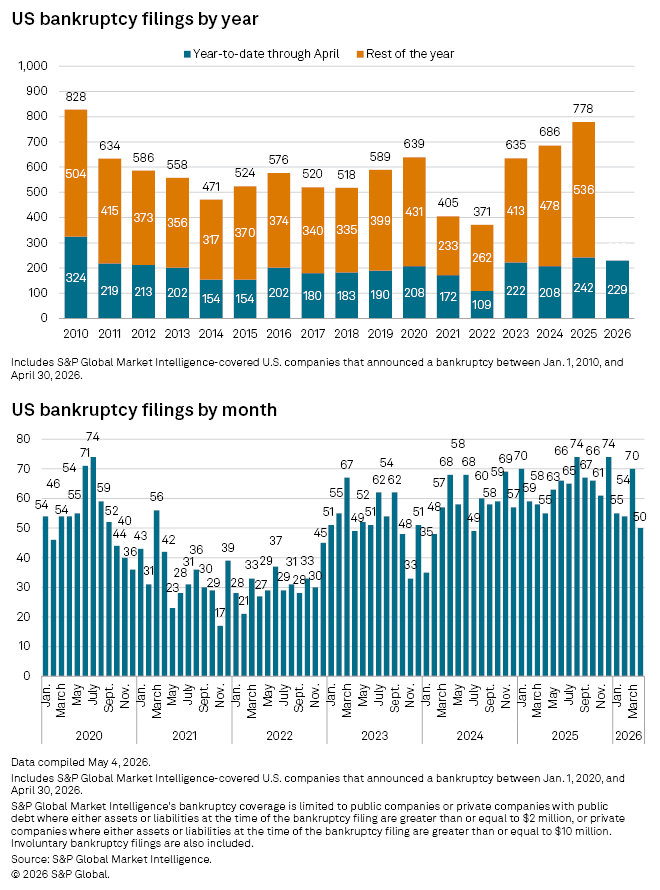
By: Michael L. Moskowitz New data released by Epiq AACER validates that insolvency filings continue to increase throughout both the industrial and customer sectors, highlighting the significance for lenders to remain watchful in securing their rights. During the very first half of 2026, subchapter V chapter 11 filings increased by 50% over the exact same duration in 2025, climbing from 1,107 to 1,663 filings.
Business personal bankruptcy filings increased 13%, while chapter 11 filings increased 28%, showing ongoing financial pressures on companies from higher loaning expenses, increased operating costs, and continuous financial unpredictability. For financial institutions, these patterns underscore the growing probability of customers, debtors, renters, and business partners seeking personal bankruptcy protection.
Insolvency procedures move quickly, and financial institutions that fail to react quickly might lose important rights. Whether the case involves a Chapter 11 reorganization, a Subchapter V proceeding, or a Chapter 7 liquidation, understanding the relevant due dates, asserting claims, examining preference and fraudulent transfer concerns, and monitoring the debtor's proposed strategy are all necessary to protecting a financial institution's interests.
Pro Tips for Managing 2026 Bankruptcy Systems
Subchapter V elections increased 28% compared to June 2025, while business chapter 11 filings increased 29%, recommending that monetary distress among organizations remains raised. As personal bankruptcy filings continue to increase, lenders should evaluate their credit practices, screen financially susceptible counterparties, and seek legal assistance quickly when a consumer or borrower declare bankruptcy.
Bankruptcy Support to Halt Garnishments
A (Lock Locked padlock icon) or implies you've safely connected to the.gov website. Share sensitive information only on official, protected sites.
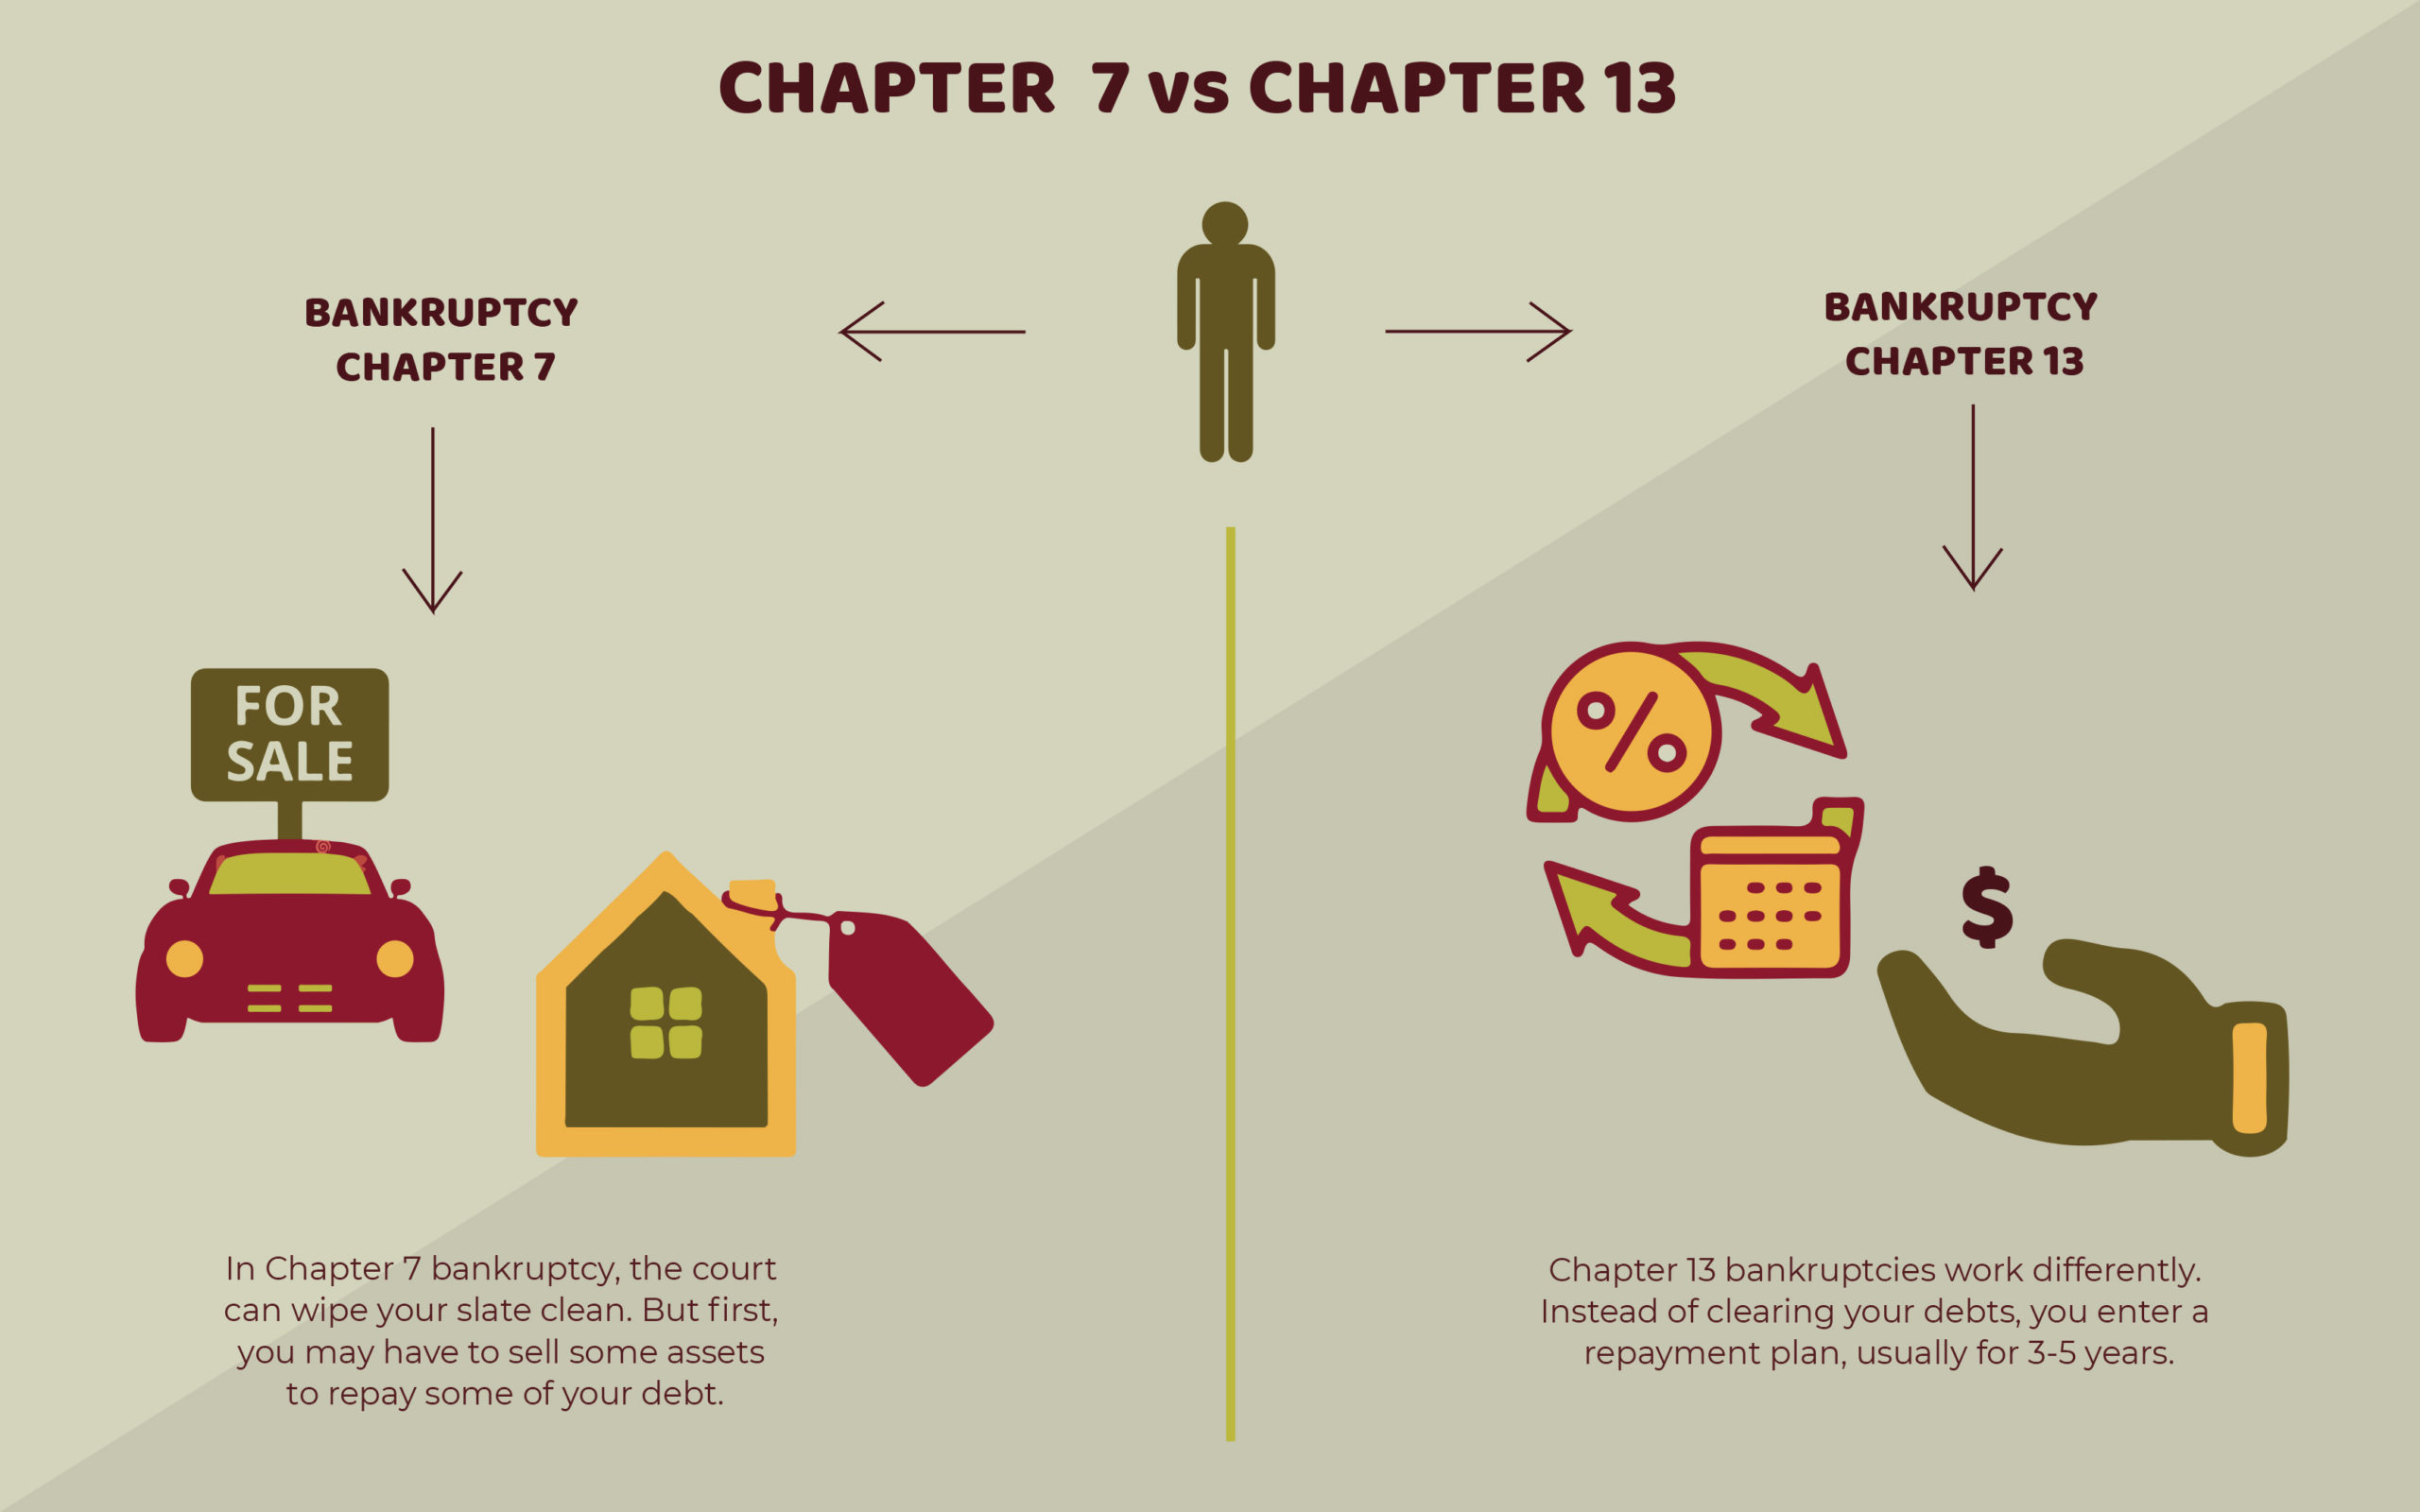
The 2005 Personal bankruptcy Act requires all private debtors who submit bankruptcy on or after October 17, 2005, to go through credit counseling within six months before declaring insolvency relief and to finish a financial management instructional course after submitting bankruptcy. Under the 2005 Personal bankruptcy Act your income and expenses will be analyzed to determine if you certify to file a Chapter 7 or if you must submit Chapter 13.
If your earnings goes beyond the mean, the remaining parts of the means test will be applied to figure out if you can file Chapter 7 or if you need to file Chapter 13. To begin the bankruptcy process you need to detail your present earnings sources; major financial deals for the last 2 years; monthly living costs; financial obligations (secured and unsecured); and home (all assets and belongings, not just real estate).
Is Chapter 7 Right for 2026 Needs?
When you have actually collected this details, either on your own or with the assistance of a lawyer, you should then determine which home you think is exempt from seizure based upon the California exemptions. To actually file, either you or your lawyer, will require to file a two-page petition and several other forms at your California district personal bankruptcy court.
If your creditors or the judge feel or learn that you have not been entirely forthcoming in your personal bankruptcy filing, it could endanger the outcome of your petition. The expense for filing a Chapter 7 personal bankruptcy is $306. This charge may not be waived but you may be able to pay it in installments.
Tips for Managing Attorney Fees in 2026If you are submitting a Chapter 13 personal bankruptcy, a proposed repayment plan need to likewise be sent. Priority claims (such as taxes and back kid support) must be paid in full; unsecured debts (like credit card financial obligation and medical bills) are normally paid in part.
2) Unsecured creditors must be paid at least as much as if a Chapter 7 personal bankruptcy had been filed. If you have actually submitted Chapter 13, you need to begin making your plan payments.

Latest Posts
Steps for Filing the Bankruptcy Claim in 2026
Serious Legal Impacts of 2026 Bankruptcy
Reviewing Chapter 7 and 13 Laws for 2026