All Categories
Featured

Comparing Chapter 7 and Chapter 13 Options
Table of Contents
Based upon the info supplied by your company, the servicer determines the amount that can be lawfully garnished from your wages. Under federal law, the U.S. Department of Education, or any firm trying to gather a trainee loan on its behalf, can garnish approximately 15% of your non reusable pay if you remain in default.
You can keep an amount that's comparable to 30 times the existing federal minimum wage per week. Your loan servicer is needed to provide you 30-days' notification before garnishing your earnings. The Notification of Intent to Garnish must include the following info about your rights: your right to demand and check copies of your student loan records your right to ask for a hearing to present proof that the garnishment need to not be enabled, and your right to get in into a repayment plan with the loan servicer.
If garnishment happened less than thirty days after the date of the notification, or if the notice doesn't have actually the needed details, that is a factor to ask for a hearing. If the servicer used inappropriate procedures, the servicer will need to start over with the right procedures. You can find detailed information on handling student loan debt in, by Amy Loftsgordon and Cara O'Neill (Nolo).
For some types of federal trainee loans (FFELs), you should request a hearing within 15 days. You can still ask for a hearing, and the garnishment will end if you win your hearing.
Whether the garnishment would enforce a financial hardship is identified according to your family size, income, and expenses. Other reasons to ask for a hearing include: You don't owe the money.
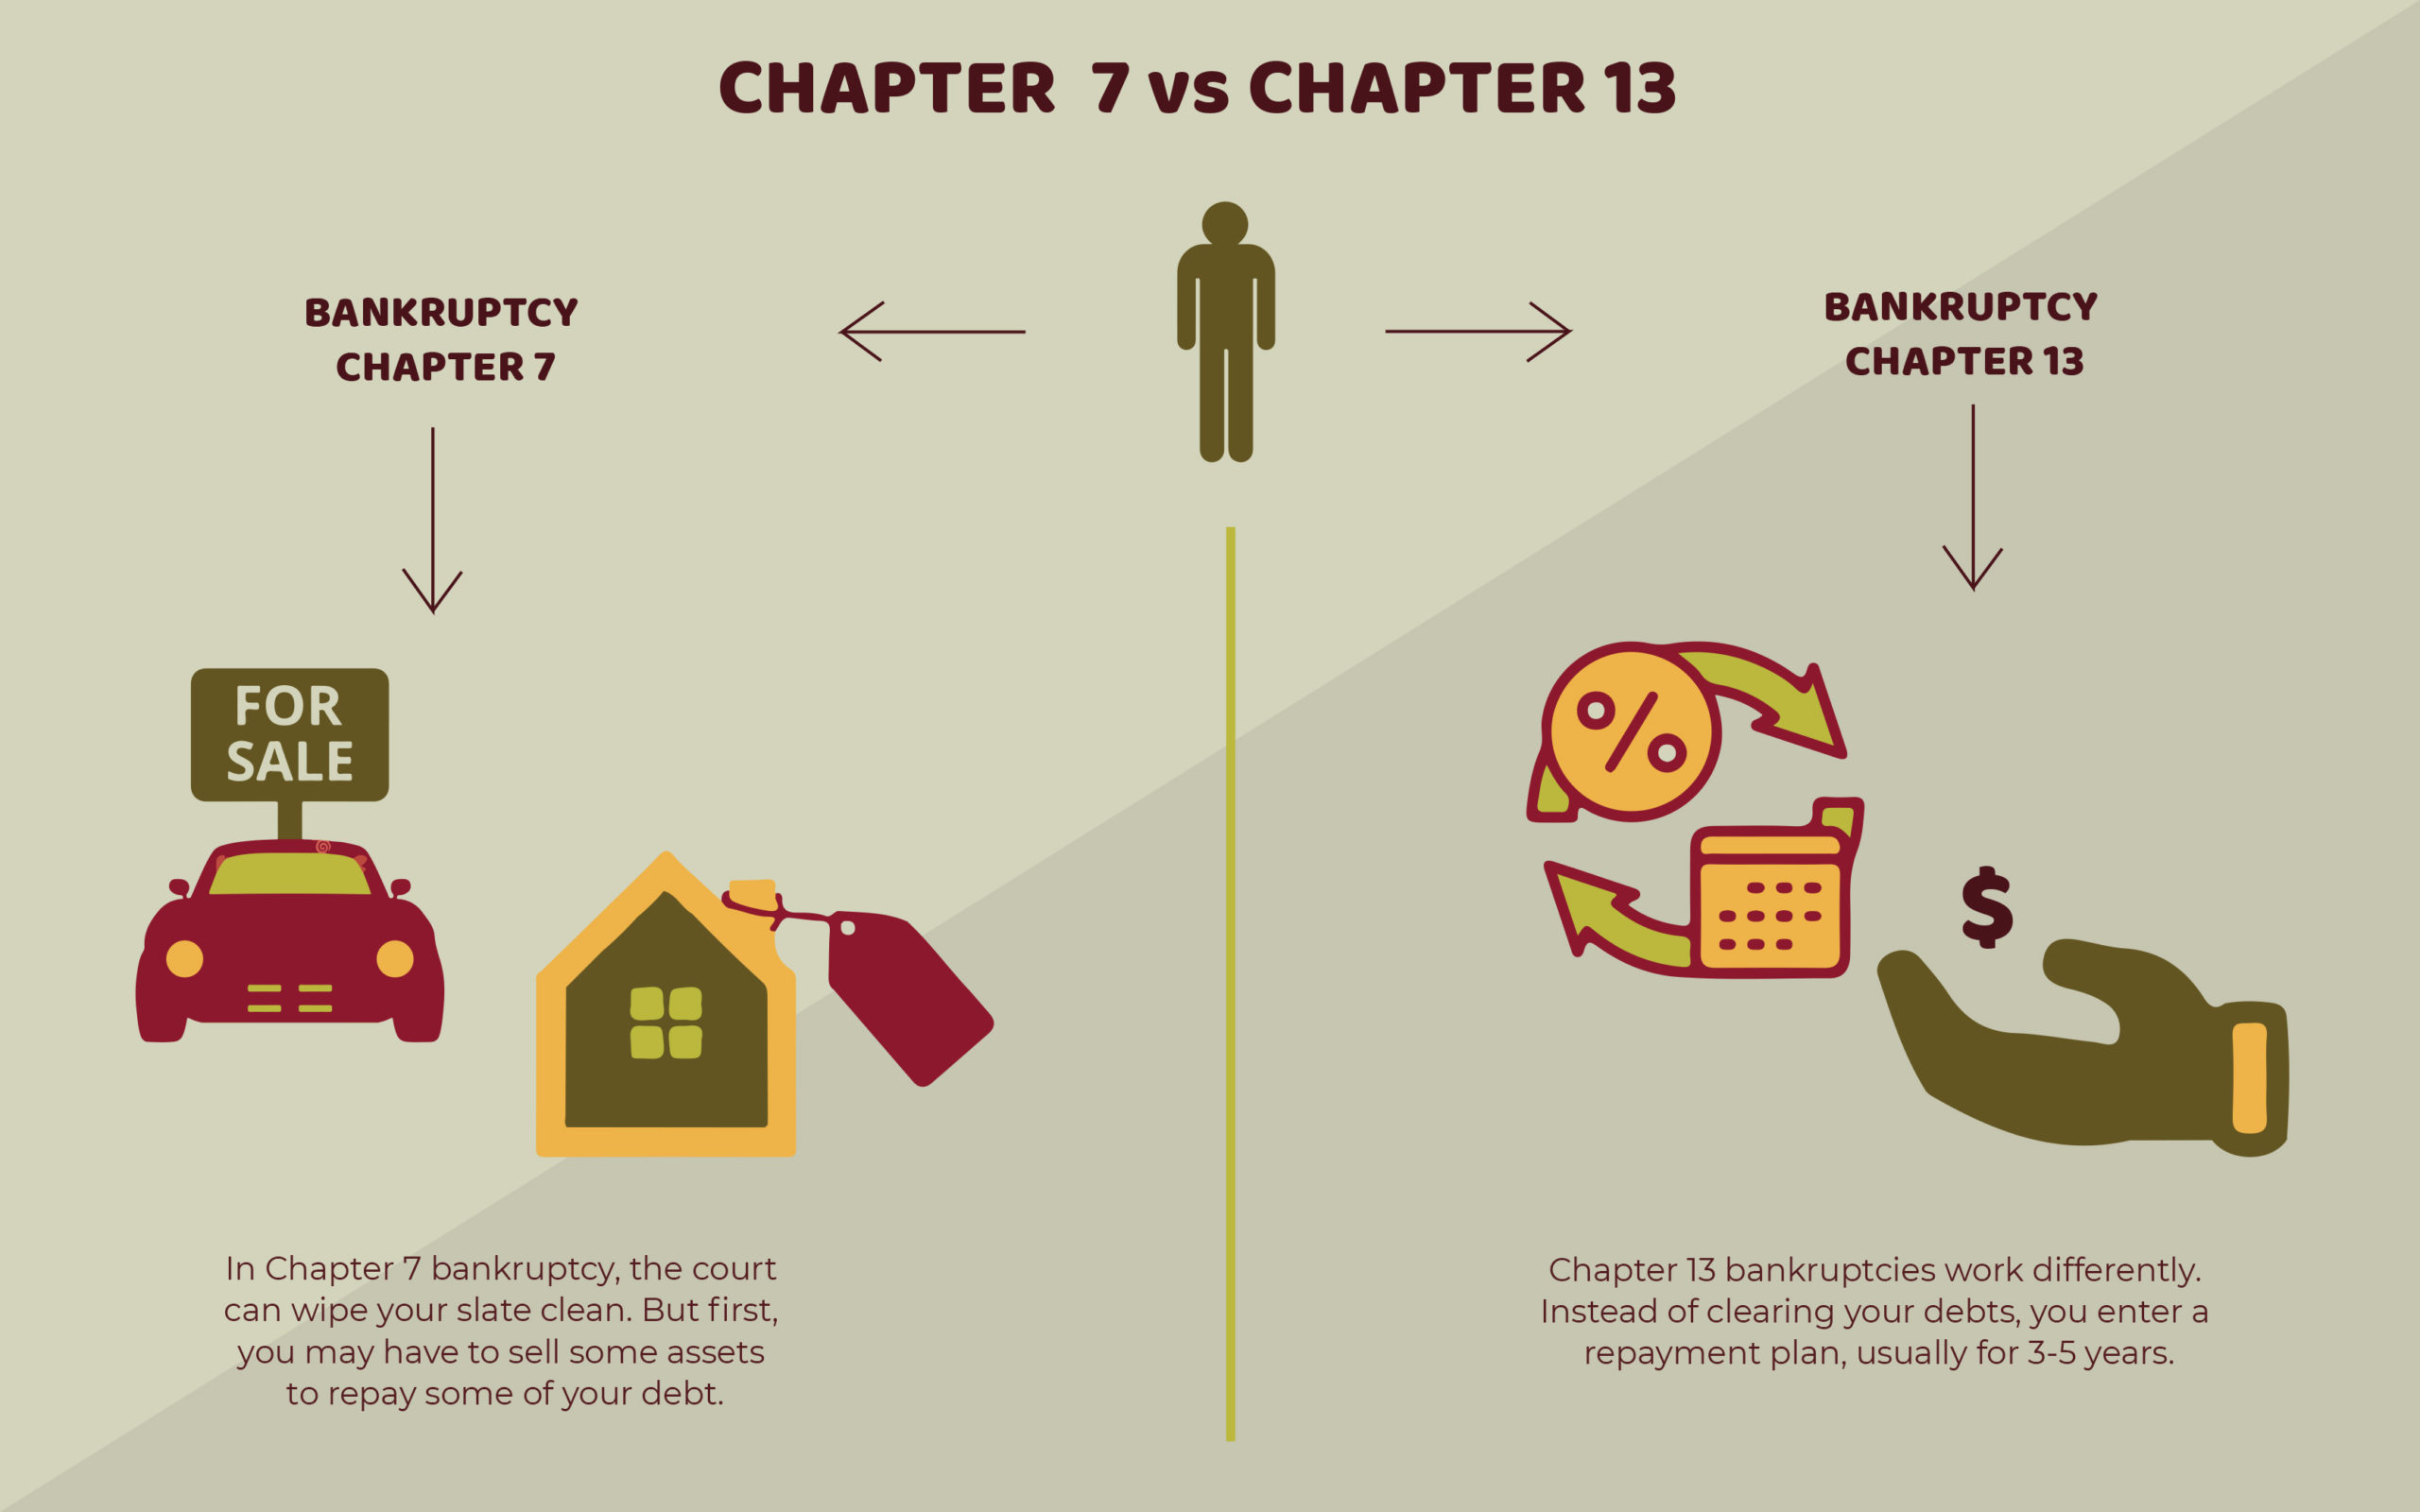
Chapter 7 and Chapter 13 Options
These include discharge due to the fact that your school closed before you might complete your program, public service loan forgiveness, and discharge for overall and long-term impairment.
The amount of cash that a student loan servicer can garnish from your income is identified using intricate rules. Once again, in general, the student loan servicer can just gather 15% of your disposable earnings through garnishment (but you can keep a quantity that's comparable to 30 times the present federal minimum wage per week).
If your income is really low, you might be exempt from garnishment. If your company is taking too much out of your income, call your loan servicer and request a correction. If essential, request a hearing to fix the quantity. Voluntary payments have lots of advantages over garnishment. The goal of any loan servicer is to establish routine payments on your debt.
Is Chapter 7 the Best Relief in 2026?
Voluntary payments have many advantages over garnishment: You won't have collection expenses contributed to your loan, you may be able to enhance your credit rating, and you may be able to reinstate eligibility for federal trainee loans in the future. Federal law says you can't be fired or otherwise retaliated against because your wages have been garnished to pay one debt.
Significant Outcomes of Filing Personal BankruptcySome states use more defense.
A student loan garnishment is the process of keeping money from an employee's wages if they are in default. You then remit the garnished wages to the Department of Education. Defaulted government trainee loan garnishment is just one type. Other types of financial obligations that cause wage garnishments consist of past due kid assistance, unpaid taxes, delinquent credit card loans, and exceptional medical expenses.
Between Chapter 7 and Chapter 13
Collections resumed in May of 2025. The Workplace of Federal Trainee Help (FSA) will send out main trainee loan garnishment notifications to defaulted debtors in the Compensation paid or payable for an employee's services can be garnished, consisting of: Wages and salaries Commissions Perks (e.g., sign-on perk) Routine payments from a pension or retirement program Personal incomes that can be garnished typically do not include tips.

Latest Posts
Steps for Filing the Bankruptcy Claim in 2026
Serious Legal Impacts of 2026 Bankruptcy
Reviewing Chapter 7 and 13 Laws for 2026